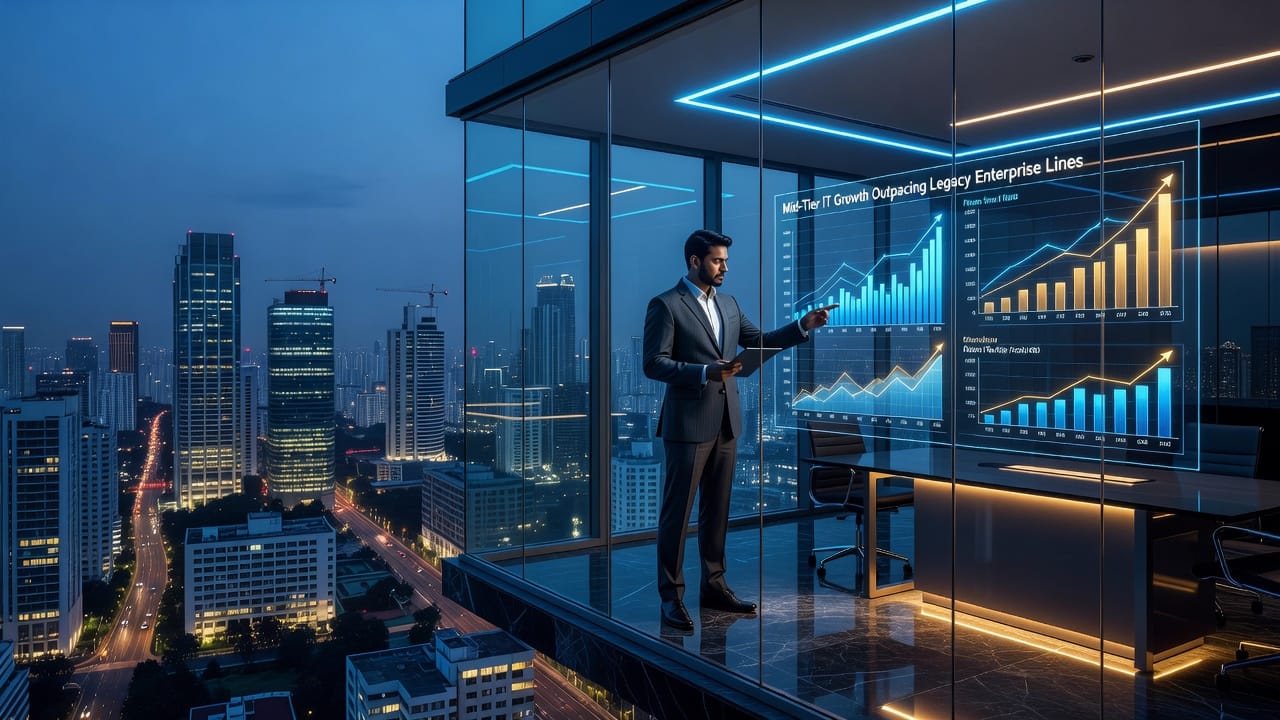


For years, tech leaders operated under the assumption that scaling a services business simply meant adding more engineering seats to a growing bench. On October 2, 2026, a report by the Business Standard revealed that JM Financial expects mid-tier Indian IT revenue growth to hit 2.7 to 13 percent sequentially in constant currency this quarter, while large caps sit between minus 0.5 and 2.6 percent. This widespread approach of linear headcount scaling quietly failed in a measurable way, as automation began eating into traditional billable hours. We named this strategic misstep the headcount-to-revenue trap, and this article serves as the operational solution for modern tech enterprises navigating artificial intelligence disruption.
The Genesis of AI Deflation in Global IT Services
As a researcher tracking the Indian startup and enterprise ecosystem closely from West Bengal, I have watched legacy business models unravel under the weight of generative tools. According to McKinsey, technological shifts redefine operational efficiencies faster than traditional management structures can adapt. Traditional legacy services are experiencing a 2 to 3 percent annual deflation driven by automated software development kits and autonomous agents. This erosion does not hit every organization with equal force. Large enterprise structures carrying massive linear headcount books find themselves exceptionally vulnerable to margin compression. When artificial intelligence systems compress a two-week coding sprint into a two-hour prompt workflow, companies billing by the hour watch their top-line revenue evaporate instantly.
This dynamic creates a profound market divergence across the subcontinent. While legacy giants struggle to decouple revenue from human hours, agile mid-sized challengers across Bengaluru, Pune, and Hyderabad are rewriting the rules of engagement. They are leveraging localized startup velocity to build proprietary IP layers on top of enterprise platforms supplied by giants like Microsoft and Google. By treating automation as an internal margin booster rather than a threat to billable time, these agile players absorb market shocks with remarkable resilience.

A Strategic Framework for Surviving and Scaling Through AI Deflation
To navigate this volatile landscape, leaders must adopt a systematic framework that shifts focus away from raw headcount expansion. I call this the Value-Realization Matrix, built on three core operational pillars. First, enterprises must uncouple revenue from resource allocation by transitioning to outcome-based and value-share pricing models. Second, internal engineering teams need upskilling via advanced developer utilities provided by platforms like GitHub and Anthropic to maximize output velocity per engineer. Third, product portfolios must pivot toward domain-specific vertical solutions rather than horizontal outsourcing tasks that software agents can easily replicate.
The firms winning in the current market cycle are not those with the largest benches, but those with the deepest domain expertise and the courage to cannibalize their own billable hours before software agents do it for them.
According to Gartner, enterprises that successfully re-price their service delivery around business outcomes routinely capture higher operating margins than their traditional peers. This structural transformation requires a cultural overhaul, moving away from tracking billable utilization rates toward measuring business impact delivered for the client. When an engineering team delivers a core automation pipeline in days instead of months, the pricing model must reward the speed and business value rather than penalize the reduction in labor hours.
Evaluating Market Resilience Across Capital Tiers
The dichotomy between large-cap stagnation and mid-tier expansion is further highlighted by recent institutional forecasts. Kotak Institutional Equities recently suggested that Infosys might face downward pressure on its forward guidance for the upcoming fiscal year. Meanwhile, mid-tier challengers continue to secure agile digital transformation mandates that bypass traditional bureaucratic procurement channels. Research from Forrester indicates that procurement decision-makers increasingly favor specialized mid-market vendors who demonstrate transparent, outcome-focused pricing structures over opaque, resource-heavy legacy contracts.
Back in July 2026, a mid-sized enterprise services firm in Chennai restructured its entire client contract portfolio from a time-and-materials model to a fixed-fee outcome guarantee, leveraging internal generative automation tools to slash delivery timelines by 60 percent. Although initial leadership fears predicted a sharp drop in quarterly revenue, the firm actually secured three new Fortune 500 accounts within ninety days because clients eagerly embraced the unmatched delivery speed and cost predictability. That operational pivot turned potential disruption into a profound competitive advantage.
Comparative Metrics: Large Caps Versus Mid-Tier IT Services
Action Plan for Executive Leaders Ahead of Upcoming Earnings
As Tata Consultancy Services prepares to report its earnings on October 8, 2026, tech founders and enterprise leaders must take immediate steps to insulate their operations from ongoing deflationary pressures. Waiting for market consensus to shift is no longer a viable strategy in a macroeconomic climate defined by rapid technological displacement. You must audit your contract pipeline today to identify exposure to linear billing models.
Here is your challenge for the next 24 hours: Select your largest time-and-materials client contract, draft an alternative outcome-based pricing proposal that rewards your team for delivery speed rather than hours logged, and schedule a strategic review call with that client before the end of the week. Do not hesitate-take control of your margin structure today.